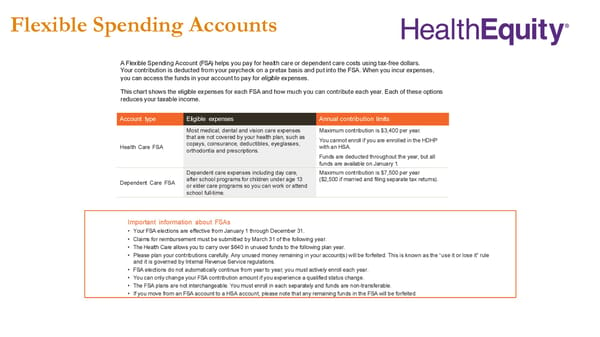
Flexible Spending Accounts Important information about FSAs • Your FSA elections are effective from January 1 through December 31. • Claims for reimbursement must be submitted by March 31 of the following year. • The Health Care allows you to carry over $640 in unused funds to the following plan year. • Please plan your contributions carefully. Any unused money remaining in your account(s) will be forfeited. This is known as the “use it or lose it” rule and it is governed by Internal Revenue Service regulations. • FSA elections do not automatically continue from year to year; you must actively enroll each year. • You can only change your FSA contribution amount if you experience a qualified status change. • The FSA plans are not interchangeable. You must enroll in each separately and funds are non-transferable. • If you move from an FSA account to a HSA account, please note that any remaining funds in the FSA will be forfeited. Account type Eligible expenses Annual contribution limits Health Care FSA Most medical, dental and vision care expenses that are not covered by your health plan, such as copays, coinsurance, deductibles, eyeglasses, orthodontia and prescriptions. Maximum contribution is $3,400 per year. You cannot enroll if you are enrolled in the HDHP with an HSA. Funds are deducted throughout the year, but all funds are available on January 1. Dependent Care FSA Dependent care expenses including day care, after school programs for children under age 13 or elder care programs so you can work or attend school full-time. Maximum contribution is $7,500 per year ($2,500 if married and filing separate tax returns). A Flexible Spending Account (FSA) helps you pay for health care or dependent care costs using tax-free dollars. Your contribution is deducted from your paycheck on a pretax basis and put into the FSA. When you incur expenses, you can access the funds in your account to pay for eligible expenses. This chart shows the eligible expenses for each FSA and how much you can contribute each year. Each of these options reduces your taxable income.
 AESOP 2026 Open Enrollment Guide Page 17 Page 19